 54 minutes ago
Goldman Sachs wrote in a note that cyclical headwinds are now largely behind Axis Bank's shares, and the underlying margins should recover from the financial year 2027 onwards, led by a favourable mix shift towards the retail/SME segment.
3 Min Read

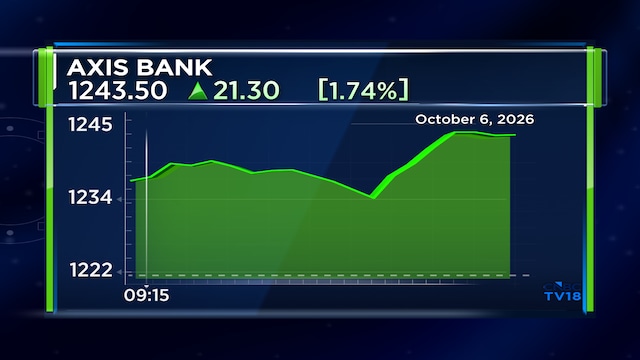
Shares of Axis Bank gained nearly 2% on Tuesday, October 6, after the lender's gross advances and deposits increased in the second quarter on both, a sequential and a year-on-year basis.
The business update prompted analysts from Goldman Sachs and Citi to reiterated their positive stance on the Mumbai-based private lender.
How Was Axis Bank's Q2 Business Update
Axis Bank's gross advances increased by 8.8% sequentially and 22.7% from last year to ₹13.84 lakh crore.
The bank's total deposits were up 5.8% from last quarter and 20.7% from last year at ₹14.52 lakh crore.
Goldman Sachs
The brokerage has a "buy" rating on the Axis Bank stock with a target price of ₹1,477 per share, indicating an upside of 20.7% from its previous close.
It reiterated that the lender's headline gross advances grew nearly 23% from last year compared to a 19% increase last quarter. Its headline deposits growth was strong at 21% from last year compared to an increase of 18% in the prior quarter from the year-ago period. This was mainly led by the FCNR deposit flows, the brokerage said.
It added that cyclical headwinds are now largely behind and the underlying margins should recover from the financial year 2027 onwards, led by a favourable mix shift towards the retail/SME segment.
Goldman Sachs said Axis Bank's valuations are inexpensive at 10 times its financial year 2028 estimated price-to-earnings ratio.
It believes the bank's risk-reward profile is attractive and supported by a rebound in its core pre-provision operating profit (PPoP) growth to 18% compound annual growth rate (CAGR) estimated during FY27-29, post a muted 11% growth estimated in the current fiscal.
Citi
Citi has a "buy" rating on Axis Bank as well and a target price of ₹1,620 per share, indicating an upside of 34.4% from its previous close.
It said the lender has mobilized $10.62 billion in FCNR(B) deposits, cornering 8% share of system-wide FCNR mobilization against a 5.3% deposit market share equivalent to more than 7.4% of its total deposits.
The brokerage said the lender's overseas book expanded to 3.5% of loans, driven by leveraged lending (43%) against FCNR balances.
Citi said that stripping the leveraged overseas book out, the lender's core gross advances growth held steady at 18.8% from last year 5.3% from the previous quarter.
Axis Bank's traction in retail disbursements should lend momentum to retail growth, while the mid-corporate/SME/SBB segments are poised to sustain their robust trajectory, the brokerage said.
It said the lender's deposits (EOP) grew 20.7% from last year and 5.8% sequentially. Adjusted for the FCNR(B)-linked inflows, deposit growth stood at 13% from last year and down 1.6% from the previous quarter.
Citi said average deposits increased 22.5% from last year and were up 7% from the prior quarter, with average current account savings account (CASA) rising 13.9% and 2.7% each.
Stock reaction
None among the 52 analysts who have coverage on Axis Bank have a "sell" rating on the stock. 49 have a "buy" rating, while three others have a "hold" recommendation. The consensus estimates of price targets implies an upside potential of 27.5% from current levels.
Shares of Axis Bank are trading 1.3% higher on Tuesday at ₹1,238.6. The stock is still down 3% so far this year.
Also Read: Angel One shares gain after trading activity recovers in September, MTF book growth continues
HomeMarket NewsHere's why analysts expect shares of this bank to rise up to 34% after its Q2 business update